The recent setback faced by DeFi in the Senate on September 15th has sparked a new challenge for Aave founder Stani Kulechov. Aave, a decentralized finance lending protocol, has been at the forefront of developing consumer and institutional products through Aave Labs.
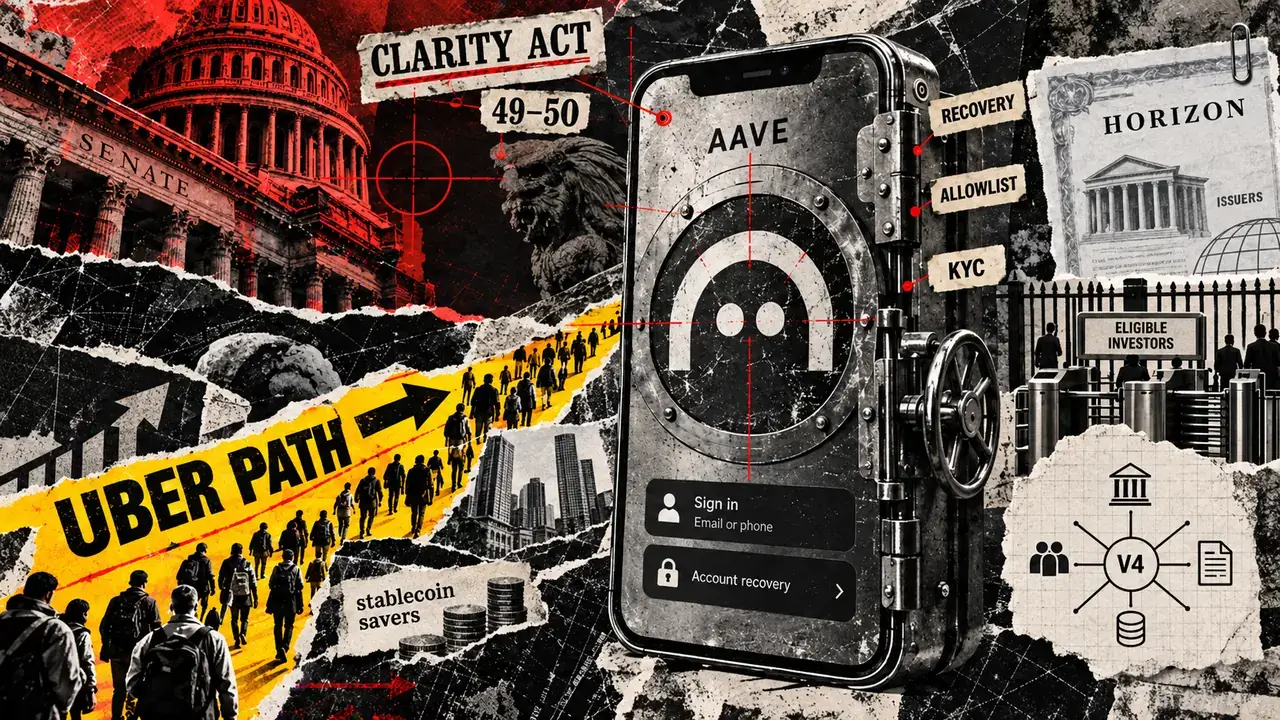
The Senate’s rejection of cloture on the motion to proceed to H.R. 3633, known as the CLARITY Act, by a narrow margin of 49-50, blocked the bill’s immediate route to floor consideration. This vote did not eliminate the regulatory authority that already exists but has raised questions about the future of digital asset market structure.
In response to this setback, Kulechov took to X to propose a new strategy for DeFi. He emphasized the need to build products that cater to the needs of millions and become “too important to ignore,” drawing parallels to the growth trajectory of Uber.
Aave’s product roadmap reflects a strategic approach to expand the reach of DeFi. By introducing consumer-friendly accounts, institutional lending against tokenized assets, and a proposed securities-finance architecture, Aave aims to attract a broader audience to the world of decentralized finance. These growth paths involve partnering with identifiable companies, issuers, service providers, and permissioned venues to enhance the functionality and accessibility of DeFi.
The consumer path focuses on simplifying on-chain saving through user-friendly account designs that mimic traditional financial apps. Aave’s smart accounts offer features such as recovery options, password-encrypted signers, and biometric verification for enhanced security and convenience. While maintaining self-custody, Aave’s operational perimeter allows for controlled movement of assets and efficient recovery mechanisms.
On the institutional front, Aave Horizon is designed to facilitate lending against tokenized securities and real-world assets. This market structure involves specific compliance requirements for collateral assets, asset issuers, and risk managers, creating a gateway for institutional players to participate in DeFi while adhering to regulatory standards.
Aave’s proposed V4 securities finance model further demonstrates the platform’s commitment to institutional scale. By structuring lending against tokenized securities through a hub-and-spoke design, Aave aims to streamline compliance processes and provide clear operational guidelines for market participants.
Despite the setback faced by the CLARITY Act in the Senate, existing regulatory frameworks still apply to interfaces, issuers, and intermediaries in the digital asset space. The SEC, CFTC, and FinCEN retain authority over securities, derivatives, and money transmission activities, respectively, based on the specific functions and activities involved.
In conclusion, Aave’s innovative product strategy not only aims to make DeFi more accessible and user-friendly but also positions the platform as a key player in shaping the regulatory landscape for decentralized finance. By engaging with both consumers and institutions, Aave is poised to influence how policymakers approach the regulation of DeFi, emphasizing the importance of responsible and compliant practices in the evolving digital asset ecosystem.