
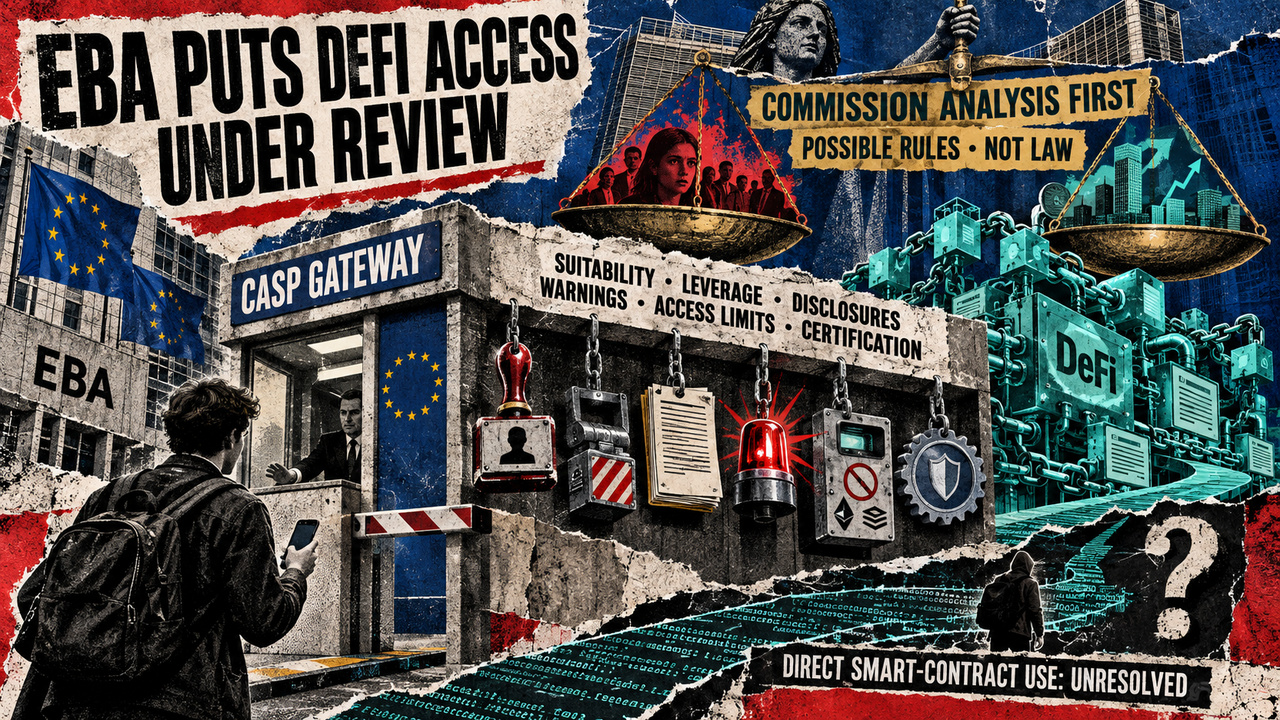
The European Banking Authority has requested the European Commission to review new MiCA regulations for cryptocurrency firms that facilitate connections between customers and DeFi loans. In its response on September 24, the EBA called for a cost-benefit analysis of potential obligations for intermediated borrowing and lending, as well as for crypto-asset service providers (CASPs) that enable clients to access DeFi lending through interfaces or products.
The EBA highlighted the risks to consumers that prompted its request for a review. It identified two potential changes that could be implemented. The first change would involve adding intermediated crypto borrowing and lending to the list of services provided by CASPs under MiCA, while the second change would establish requirements for CASPs that facilitate access to DeFi lending protocols.
The Commission will need to evaluate the scale of these activities, retail participation, and the severity of the risks before deciding on any legislative action. Measures such as suitability tests, leverage caps, and enhanced disclosures could be implemented to address borrowing risks. Additionally, warnings about the lack of regulatory safeguards in truly decentralized protocols and certification of lending protocols for resilience to cyberattacks were suggested by the EBA.
Another proposal outlined in the response concerns tokens issued by entities without the required MiCA authorization. CASPs could potentially be restricted from intermediating or facilitating borrowing and lending activities involving such tokens, limiting their access to certain lending activities.
The response also highlighted potential consumer harms associated with incomplete information about fees, yields, collateral requirements, leverage risks, and issues like commingling, hacks, and poor recordkeeping. It emphasized the importance of creditworthiness checks and preventing over-indebtedness.
The EBA’s proposals aim to establish safeguards for DeFi lending, but none of these measures have been enacted as rules yet. The Commission is currently seeking feedback through a consultation process that will inform its report on MiCA’s application and developments in the crypto market. Depending on the feedback received, the Commission may propose legislative action in the future.
The EBA’s document underscores the need for clear obligations for firms and customers engaging in different routes to access DeFi lending, including interfaces, intermediaries, and products providing exposure to DeFi. The distinction between these routes will require careful consideration to ensure regulatory compliance and consumer protection in the evolving crypto landscape.